Key Takeaways
- The lowest scheduled payment is not necessarily the least expensive option.
- Compare the APR, fees, number of payments, due dates, and total repayment amount.
- A shorter term can mean higher payments but a lower overall borrowing cost.
- Late-payment rules, automatic withdrawals, and early-payoff terms can affect the real cost.
- A workable repayment plan should fit the budget without requiring another loan.
Whether the need is a car repair along the Wasatch Front, an urgent utility bill, or an expense that arrives before the next paycheck, borrowing decisions can feel time-sensitive. Utah residents considering no credit loans in Utah should slow down long enough to compare the full cost, payment timing, and rules of each offer. A loan that appears manageable because of its monthly payment may cost more over time than another option. Looking beyond the payment amount can help borrowers choose an arrangement that addresses the immediate need without creating a larger budget problem next month.
Why Cost Comparison Matters
Two loans for the same amount can lead to very different total costs. One lender may spread repayment across more months, while another may charge fewer fees or allow early payoff without an added charge. A recent report on short-term borrowing for everyday essentials also highlights why payment schedules and the consequences of missed payments deserve close attention. Before comparing offers, write down the exact amount needed. Borrowing extra simply because it is available can increase the payment and total amount due. Then compare each lender using the same checklist rather than relying on a single advertised figure.
What To Review In A Loan Offer
Place these details side by side for every offer under consideration:
- The amount actually received after any deducted fees.
- The annual percentage rate, or APR.
- The finance charge and any origination or processing fee.
- The total amount scheduled to be repaid.
- The number of payments and whether they are weekly, biweekly, or monthly.
- The first payment date and every due date afterward.
- Late fees, returned-payment fees, and collection terms.
- Whether early repayment is allowed and how it affects the balance.
- Whether the agreement permits renewal, extension, or rollover.
APR Versus Interest Rate
The interest rate describes the rate charged on borrowed money. APR is broader because it is designed to reflect the cost of credit on an annual basis and may incorporate certain finance charges. Neither number replaces reading the agreement, but APR can make it easier to compare similarly structured offers. Ask whether the rate is fixed or variable, and confirm which fees are included in the quoted figures. A low stated interest rate may not tell the whole story if the offer includes significant charges or a repayment structure that does not match the borrower’s cash flow.
Fees, Payment Dates, And Loan Terms
Small fees can become meaningful when money is already tight. Review application, origination, late fees, returned payments, and optional service charges. Utah borrowers can use the state regulator’s guidance on comparing rates, fees, and prepayment terms as a reminder to read every cost disclosure before signing. Payment dates matter just as much as payment size. If an automatic withdrawal occurs before payday, an otherwise affordable loan can lead to an overdraft or a missed payment risk. Use this quick review process:
- Put each due date on a calendar.
- Match every payment to expected income dates.
- Check the authorization for automatic withdrawals.
- Find the exact consequence of paying late.
- Confirm whether paying early reduces the remaining cost.
A Simple Cost Example
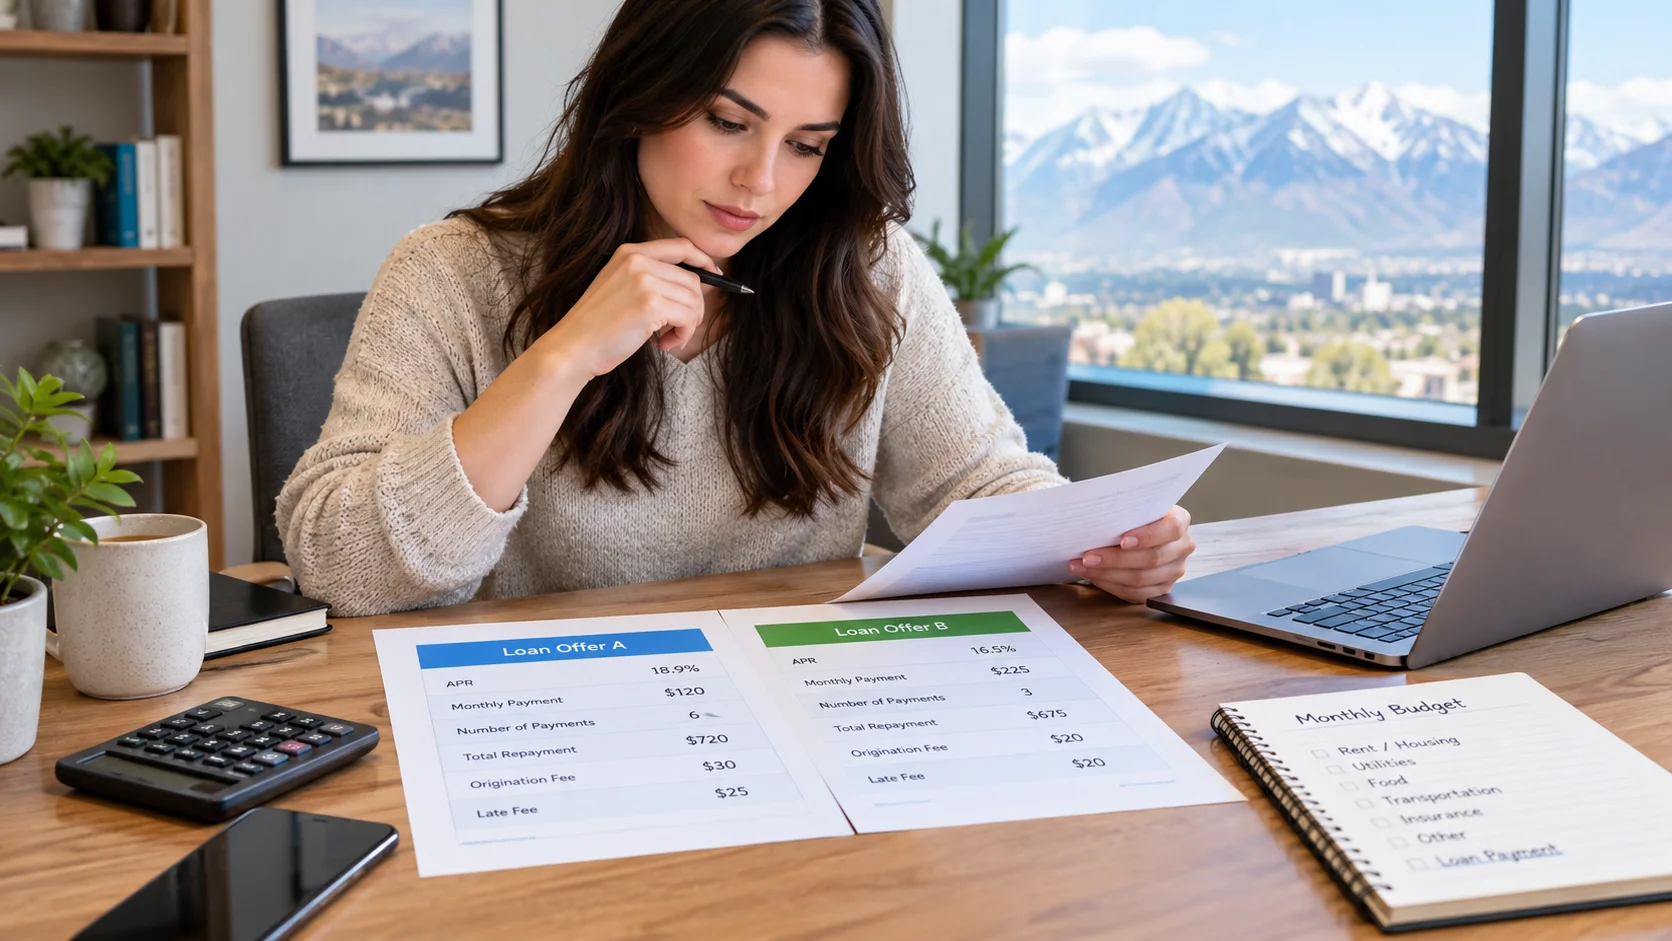
Imagine a borrower needs $600. Offer A requires six monthly payments of $120, for a total repayment of $720. Offer B requires three monthly payments of $225, for a total repayment of $675. Offer B has the larger monthly payment, but it costs $45 less overall. This does not automatically make Offer B the better choice. If the borrower cannot reliably afford $225 per month, a missed payment could incur fees or create additional financial strain. The right comparison considers both total cost and whether each payment fits safely within the household budget.
Questions To Ask Before Borrowing
- How much will I receive after all fees are deducted?
- What is the full dollar amount I will repay if every payment is made on time?
- When is the first payment due?
- What happens if I am late or a payment is returned?
- Can I pay the balance off early?
- Does the agreement allow renewals or extensions?
- Will payment activity be reported to consumer reporting agencies?
Warning Signs To Watch For
Be cautious when a lender pressures someone to sign immediately, avoids giving clear cost details, or makes promises that seem to guarantee approval for every applicant. Other concerns include requests for unusual upfront payments, renewal terms without a defined payoff path, difficult-to-calculate late fees, or documents that differ from the verbal offer.
Read the complete agreement and keep a copy. If a term is unclear, ask for an explanation in writing before accepting the loan.
Alternatives And Repayment Planning
Borrowing is not the only possible response to a short-term cash gap. A utility provider may offer a payment arrangement. An employer may offer earned-wage access. A local credit union, nonprofit credit counselor, or family support network may also present options, depending on the situation. Delaying a nonessential purchase can sometimes protect the budget as well. For a repayment plan, list take-home income, rent or mortgage, food, utilities, transportation, insurance, and other required bills. Set aside room for irregular expenses, then identify what remains for a loan payment. For example, a Utah renter facing a repair bill before payday may find that a payment arrangement with the repair provider is less risky than taking a payment that leaves no cushion for groceries or fuel.
Common Questions
Is a lower monthly payment always better?
No. A lower payment may mean a longer repayment period and a higher total amount paid. Compare both the payment and the complete repayment figure.
Can a short-term loan cost less overall?
It can, particularly when the term is shorter, and fees are lower. However, the larger scheduled payment must still be realistic for the borrower’s budget.
What if a payment may be missed?
Contact the lender before the due date, ask about available options, and request any arrangement in writing. Addressing the issue early may be more manageable than waiting for additional charges to appear.
Final Thoughts
Comparing short-term loan costs takes more than checking the amount due each month. Utah borrowers should evaluate APR, fees, payment dates, total repayment amount, penalties, and early payoff rules before deciding. It can also help to review the loan term, understand how often payments are required, and check whether any additional charges could increase the overall cost of borrowing. Comparing offers from multiple lenders may make differences in rates, fees, and repayment terms easier to identify. Borrowers should also consider whether the expected payment fits comfortably within their existing budget and whether taking on the loan could affect other monthly expenses. A careful side-by-side review can make it easier to identify an option that meets an immediate need while protecting the next month’s budget and reducing the risk of unexpected repayment costs.